


Financial headlines feel personal when you retire. Whenever a high-flying stock falls by double digits in a single trading session or a company’s management revises its earnings guidance downward, the instinct is to act – sell, rebalance, Some?.
But for retirees who are trying to protect what they have saved over decades of hard work, the most dangerous reactions to market volatility are those rooted in emotions. Working Sell off in artificial intelligence (AI) stocks This is not necessarily a warning sign that you need to take immediate action.
Rather, it may be a much-needed reminder that your position may be wrong to begin with. What to do here.
Image Source: Getty Images.
Chasing narratives is a big problem when building sustainable assets
Retirees who indexed heavily on AI-adjacent names – semiconductors, cloud infrastructure companies, or enterprise software platforms – likely did so because the story looked attractive. To be fair, the tech sector’s returns over the past few years have validated this thesis.
However, smart investors understand that focused investing for a single Subject Brings weakness to your portfolio. This is the last thing you want in retirement.
When a high-growth sector enters a recovery, it rarely does so gradually. Over the past few months, growth stocks have shown huge differences on capex surprises and a change in feeling Around the pace of AI monetization.
Retirees run the risk of being locked into these valuation de-ratings more permanently than the paper losses a beginning investor would suffer. In turn, poorly timed losses in retirement can reduce the stability and longevity of a portfolio. Fortunately, the solution isn’t to abandon equities altogether. This is simply to widen your aperture.
How the S&P 500 does the heavy lifting for retirees
S&P 500 One of the most flexible instruments available for long-term investors. The index gives you exposure to the largest US companies and automatically rebalances as winners advance and lag behind.
If AI someday delivers on its promises, the S&P 500 is poised to gain, as its holdings include all the companies developing, monetizing, and purchasing AI. Conversely, if AI disappoints in the coming years, the index Diversity Concentrated volume keeps your portfolio from experiencing negative pressure.
In particular, the S&P 500 has an unmatched long-term track record when benchmarked against a single sector thesis. The index has survived the dot-com bubble, the 2008 financial crisis, a global pandemic, and every macro-driven scare in between.
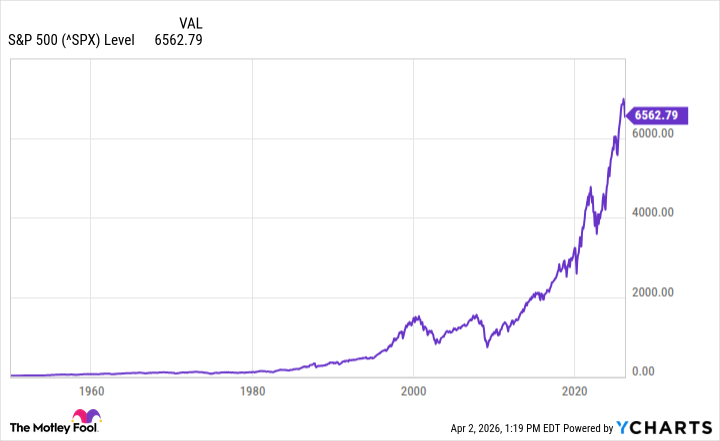
Retirees who stayed the course and invested in broad index funds through these cycles not only recovered — they managed to grow their wealth. Time to Market–No market timing –The key pillar supporting wealth preservation at a stage when capital preservation matters most.
How should retirees invest now?
If you are retired and sitting in AI positions that are at risk, the question is not whether to sell. The point is whether you are comfortable reducing your cost basis today and adding to those positions.
If the answer is no, then it’s time to reduce this concentrated exposure and shift it to broad index funds SPDR S&P 500 ETF Trust (detective 0.36%)The Vanguard S&P 500 ETF (woo 0.33%)Or Invesco S&P 500 Equal Weight ETF (RSP 0.23%). As a sweetener, you may be able to use any losses from AI stock clear your tax liability.
In addition to these rebalancing efforts, it would be wise for retirees to hold short-term bond or money market funds to help cover basic living expenses. This approach provides a liquidity buffer and allows you to avoid selling equity to raise cash during market downturns.
The AI revolution may yet be contested by its most ardent supporters. But a retirement portfolio should not bet the house on this, or any, narrative. Building a retirement fund is essential to surviving every economic cycle – both euphoric and brutal. This is exactly what broad market performance via the S&P 500 is designed for.
