


Artificial Intelligence (AI) stocks face headwinds in 2026, as shown by 3% year-to-date decline Global X Artificial Intelligence & Technology ETFWhich invests in companies developing AI hardware and software, in addition to using the technology in their operations.
NVIDIA (NVDA +1.71%)Arguably the biggest name in AI, one that has shared the pain of the wider market. nvidia stock is down about 1.6% in 2026 (and was down as much as 12% at the end of March), even though its business shows no signs of slowing down. This pullback seems like a buying opportunity, especially considering that this AI pioneer could see its shares double by the end of the year.
Let’s take a look at why Nvidia could see a parabolic surge in its stock price in 2026.
Image source: Nvidia.
Nvidia’s great revenue pipeline is going to supercharge its growth
Nvidia’s fiscal year 2026 (which ended on January 25, 2026) ended on a high note. Its fiscal fourth quarter revenue rose 73% year over year to $68 billion, surpassing full-year growth of 65% to $216 billion. Its earnings per share rose 82% year over year in the quarter, while annualized earnings rose 60% to $4.77 per share.
The numbers are impressive, but what’s worth noting is that Nvidia is likely to perform even better in the new fiscal year (which coincides with the majority of 2026). The chipmaker’s Blackwell and Vera Rubin chip platforms have been a huge hit with customers, driven by their ability to tackle both AI model training and inference workloads.
As a result, Nvidia expects a whopping $1 trillion in revenue from Blackwell and Rubin chip systems in 2026 and 2027. This is double the originally projected revenues for these two platforms in 2025 and 2026, which clearly suggests that the latest Rubin systems are gaining great traction.

today’s change
(1.71%) $3.15
current price
$187.06
key data points
market cap
$4.5T
day limit
$184.32 -$187.20
52wk range
$95.04 -$212.19
volume
836K
average volume
179m
gross margin
71.07%
dividend yield
0.02%
Again, this is not surprising, as Nvidia claims that its Rubin chips are 3.5 times faster than Blackwell during AI model training and 5 times faster for inference applications. Therefore, Nvidia’s data center business still has significant room for growth.
Nvidia projects record $193.7 billion in data center revenue in fiscal year 2026, up 68% from last year. The $1 trillion guidance for the next few years points to substantial growth in this segment’s revenues, which is why analysts expect its bottom line to surge 74% this year to $8.29 per share.
Importantly, Nvidia’s fiscal 2027 earnings estimates are moving higher, a trend that may continue amid heavy investments in AI data centers.
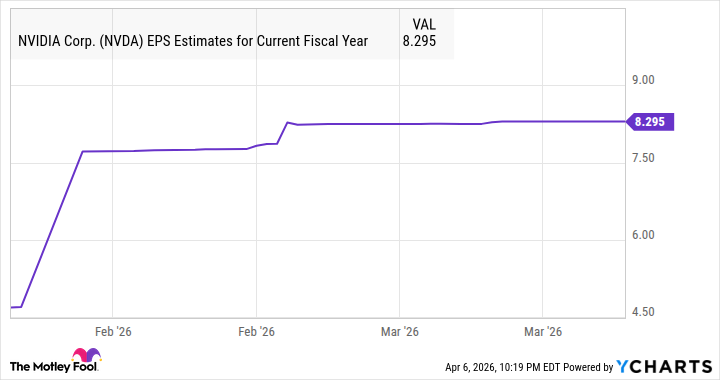
data by YCharts. EPS = Earnings per share.
The market is not rewarding this stock for its excellent growth
Given the points discussed above, a retreat of semiconductor stocks in 2026 does not seem appropriate. As a result, Nvidia is trading at an attractive 21 times forward earnings, which is a slight premium. S&P 500 The forward yield of the index is a multiple of 21. Nvidia, however, deserves to trade at a much higher premium to the S&P 500.
I say this because its earnings growth in the current financial year is expected to be more than 4 times the average 17% earnings growth of S&P 500 companies. So don’t be surprised if that happens ai stock After one year the premium commands a multiplier.
Considering that Nvidia trades at 42 times earnings due to its amazing growth (double the multiple of the S&P 500), its stock could reach $348 based on earnings estimates of $8.29 per share. This is almost double its current price, which is why it would be a good idea to buy it before you step on the gas.
