


Last summer, Lorena Alvarado Hill received a series of unexpected medical bills.
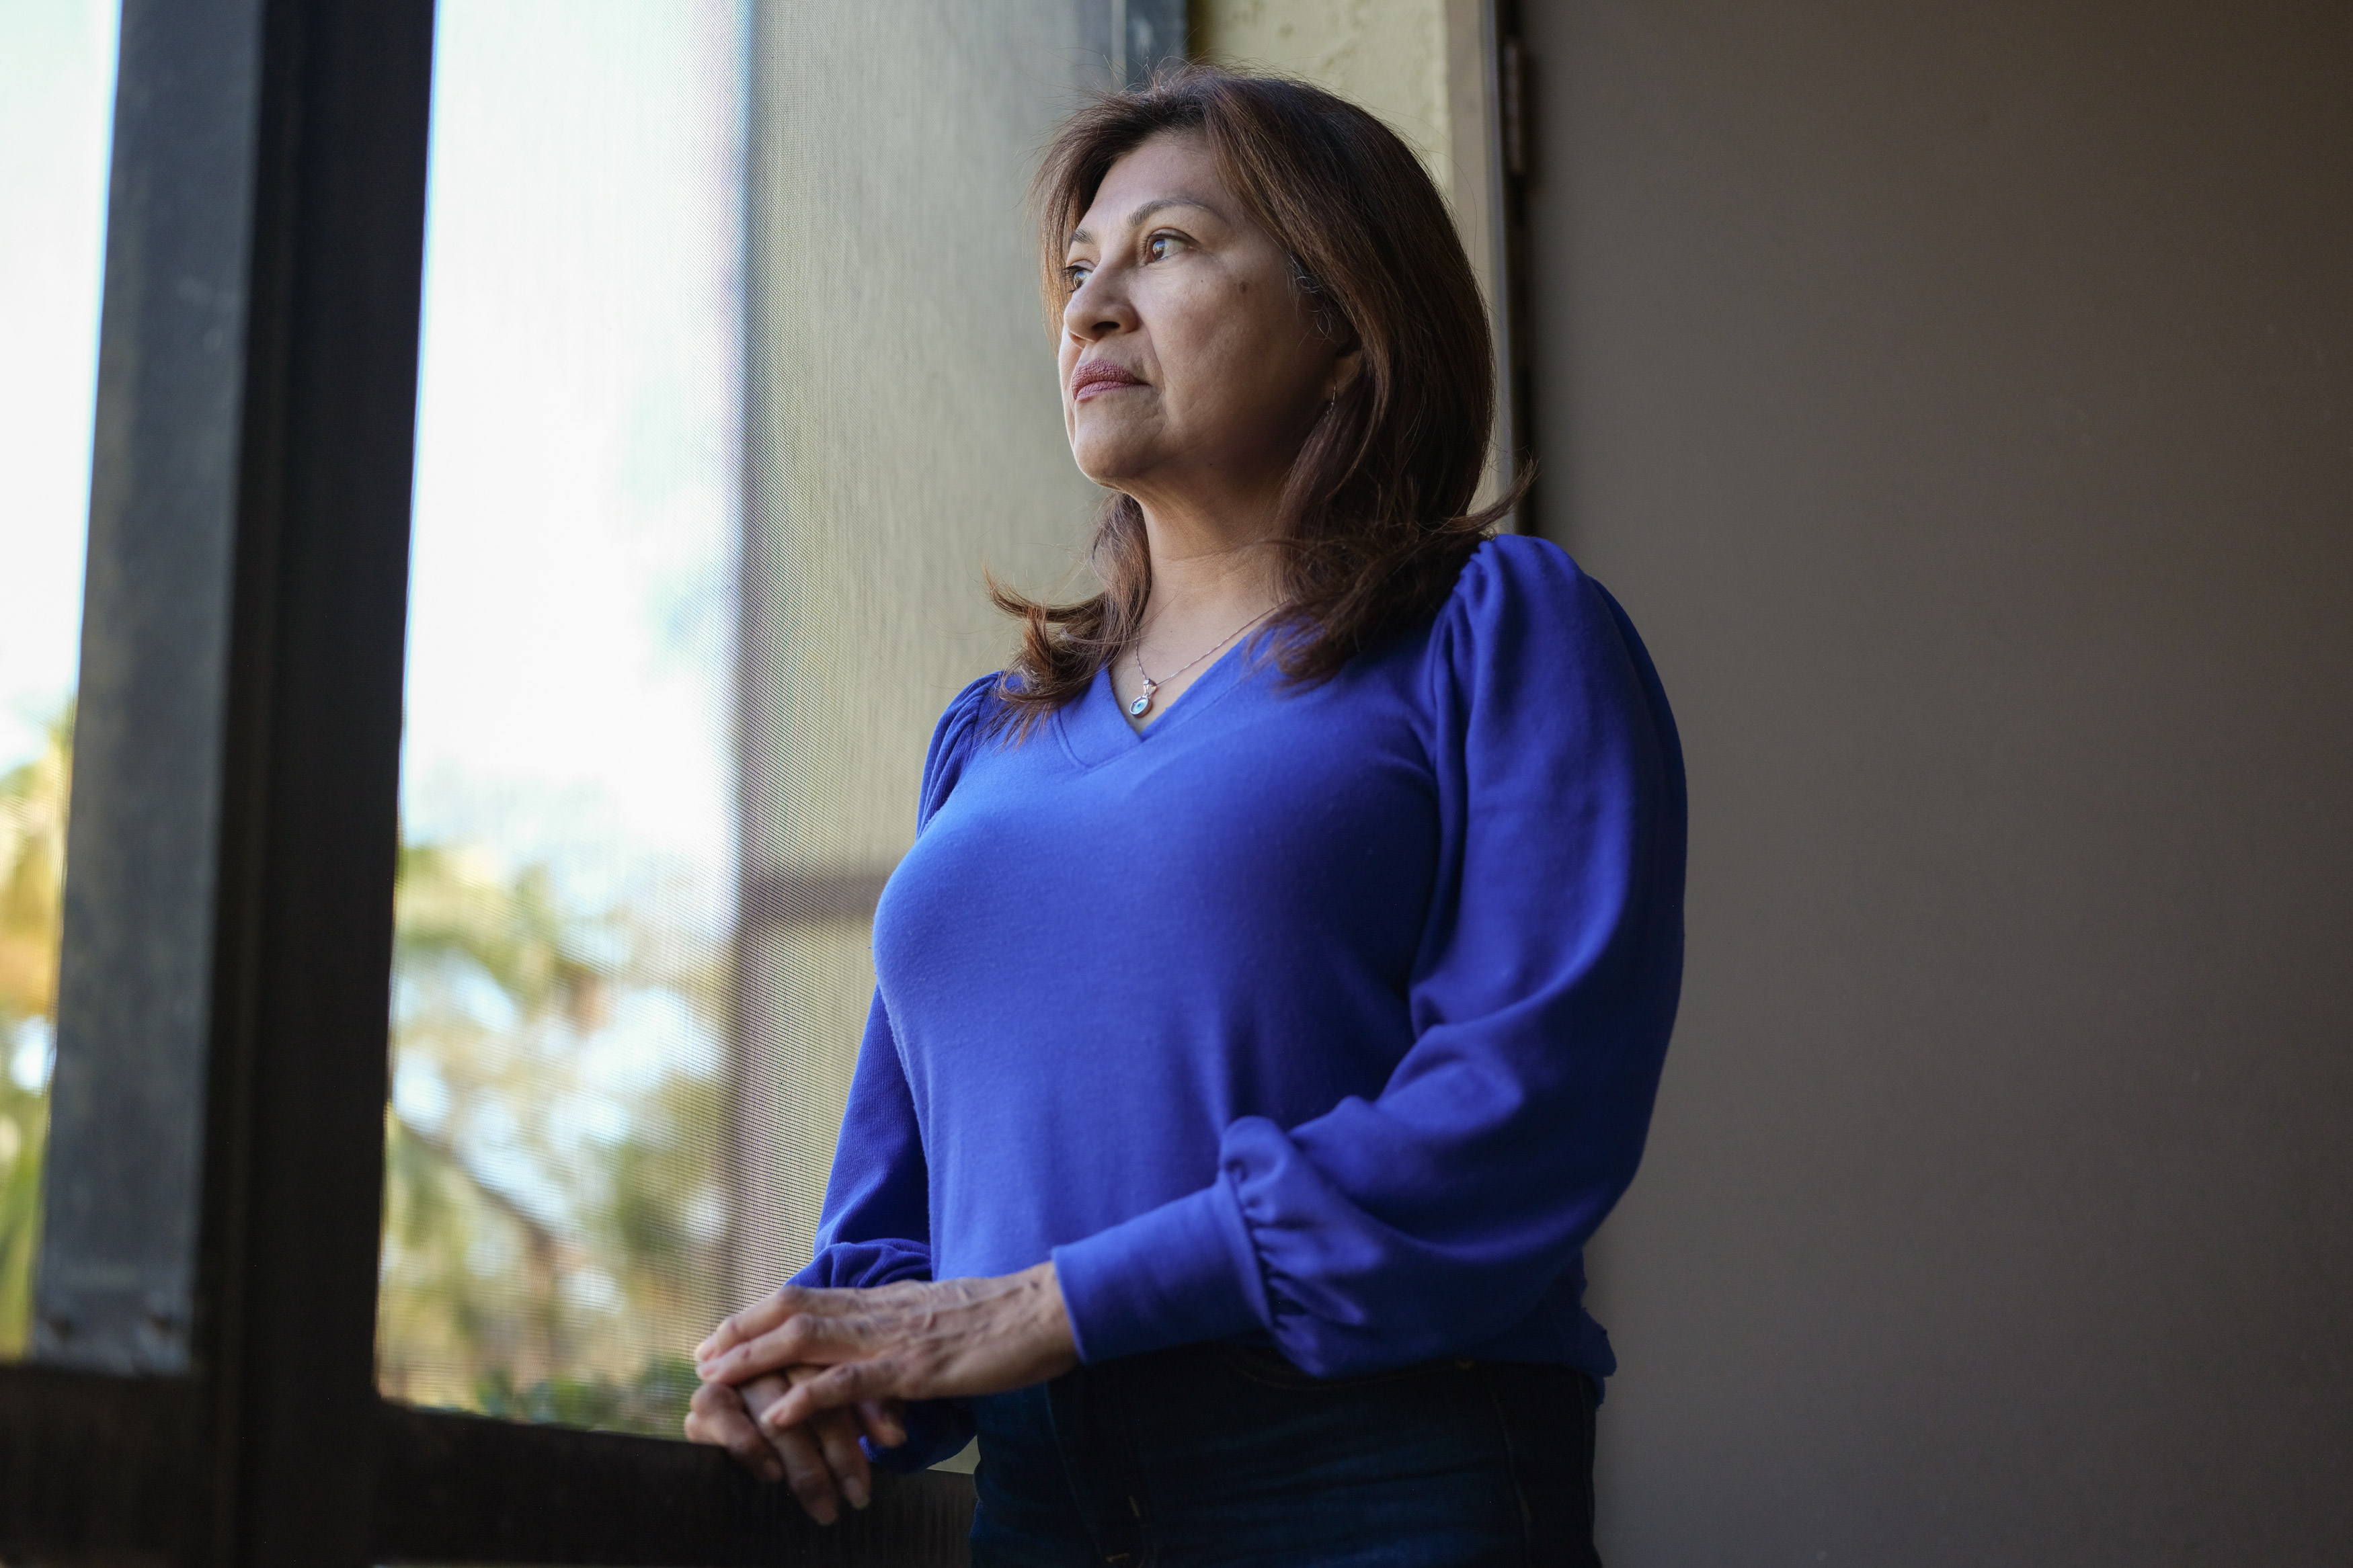
A teacher’s aide in Melbourne, Florida, Hill is a single mother who works shifts at J.Crew on weekends to send her daughter to college. Hill and her mother, who lives with her, were enrolled in an insurance plan through HealthFirst.
Hill paid nothing for the premiums on the government-subsidized plan, which previously covered her scans and other appointments.
Then the bills came.
Hill was on the hook for a $2,966.93 MRI, plus a half-dozen doctor visits costing about $200 or $300 each. Without that kind of money, Hill said, she put some into bill payment plans and tried to figure out what went wrong.
She was surprised to learn that her insurance had been canceled due to “non-payment of premium”.
medical service
A health insurance plan purchased through the Affordable Care Act federal exchange, Healthcare.gov.
Bill
Monthly premiums billed for 1 cent, which increased incrementally to 5 cents in subsequent months.
Billing Problem: Small Bill, Big Results
Premium subsidies for ACA plans are automatically recalculated when coverage changes due to a life event, such as marriage, job change, or a child turning 26. In June, Hill removed her mother from the family’s group plan because she turned 65 and became eligible for Medicare and Medicaid.
The change triggered a recalculation of Hill’s monthly premium contribution, increasing it from $0 to 1 cent. She said she thought the amount was so small that she couldn’t pay it with her credit card.
Hill acknowledged that she received some bills that read, “You may lose your health insurance coverage because you have not paid your monthly health insurance premium.”
But she said her doctors collected the usual payments during subsequent visits and her insurance broker told her not to worry, reassuring her that the plan was “active.” That said, Hill estimated that the 1 percent monthly premium was probably a rounding error that could not have resulted in termination.
On November 22, she received a letter that read “Important: Your health insurance coverage is expiring.” Its last day of coverage was listed as July 31, nearly four months earlier.
“I panicked,” Hill said. “I couldn’t sleep that night.”
She made an appointment with her broker the next day, who called HealthFirst for clarification. The news was even worse: Not only was her insurance canceled, but the 5 percent bill could be sent to a collection agency.
Hill takes out a loan to pay for her daughter’s college expenses. “I can’t ruin my credit,” she said.
Others have lost coverage because of small amounts, said Sabrina Corlett, co-director of the Center on Health Insurance Reform at Georgetown University. “This woman’s situation is not that unusual with increased subsidies,” he said.
The American Rescue Plan passed in 2021 increased the amount of government assistance available to ACA plan holders. The increased subsidies, which Congress let expire at the end of last year, meant low-income enrollees would have to pay little or nothing for their premiums.
The Biden administration found that, in 2023, nearly 81,000 subsidized ACA insurance policies were terminated because the enrollee owed $5 or less. More than 103,000 were canceled for owing less than $10.
Biden administration health officials said that’s to prevent that type of loss of coverage, which would potentially disproportionately affect low-income people. Gave flexibility to insurers To allow ACA enrollees to maintain coverage if they owe less than $10 or 95% of the premium cost.
Insurers were required to keep the insurance active for a 90-day “grace period” to give enrollees time to respond. That’s why Hill’s doctors initially charged her a co-payment and didn’t send a bill, as if nothing had changed.
The Biden administration’s “flexibility” rule took effect Jan. 15, 2025, though not every insurer chose to offer leniency to those who owed small amounts.
The Trump administration lifted the rule on August 25, completely eliminating the protections in the name of combating fraud and abuse.
Resolution
Concerned about cancellations, thousands of dollars in bills, and the threat of recovering more than 5 cents, Hill researched insurance law and took countermeasures.
She filed a complaint with HealthFirst and the Florida Department of Financial Services in December, seeking to waive her 5-percent balance and retroactively reinstate her policy, citing state and federal laws that apply to her situation.
Specifically, they wrote, “Creditors are not required to collect credit-card balances of $1.00 or less, and consumers are not required to make payments,” adding that “all major insurers and payment processors in Florida follow a 1-percent write-off policy.”
He said HealthFirst’s policy was to respond to complaints within 30 days.
Thirty days came and went, but Hill said she didn’t hear back — and new bills from her canceled policy kept coming.
Despite her disappointment, Hill said, all of her doctors were contracted with HealthFirst, so she re-enrolled for 2026.
HealthFirst spokesman Lance Skelly initially said the case was “still in the appeals/grievance process.” In a follow-up email, he said HealthFirst had followed the law In canceling Hill’s policy.
“To step back from what is legal, it is absolutely ridiculous,” Corlett said.
A few weeks after a reporter’s question to the insurer, Hill said he looked at his billing statements for all Medicare services he received through 2025 and was pleasantly surprised to find the balance owed had been adjusted to $0.
But she said she would also like HealthFirst to reimburse what it has paid and to still be paid for the bills it has placed on payment plans.
takeaway
Even small bills can have big consequences.
With the automation of more health billing decisions, irrational outcomes have become increasingly common.
“One percent?!” Hill said. “No human being would do that!”
It may be tempting to dismiss the small debt notice, but it’s important to take it seriously. Contact the insurer and get a human involved.
And while insurance policies have grace periods that keep coverage in place if you miss a payment, some aren’t very long. For subsidized ACA Marketplace plans, the term is 90 days, but others only last 30 or 45 days.
Missing a payment could mean losing coverage. So it is important to keep a close eye on the premiums to ensure that they are paid.
Bill of the Month is a crowdsourced investigation kff health news And Washington Post Welfare Who analyzes and interprets medical bills. Since 2018, the series has helped many patients and readers reduce their medical bills, and has been quoted in statehouses, the US Capitol, and the White House. Do you have a confusing or embarrassing medical bill you want to share? tell us about it!
